Moving to San Luis Obispo County? Ask These 4 Questions
| Criteria | Coastal (Cambria, Morro Bay, Shell Beach) | Inland Corridor (San Luis Obispo, Edna Valley) | South County (Arroyo Grande, Nipomo, Grover Beach) |
|---|---|---|---|
| Typical Summer Highs | 60s, marine layer into July | Low 80s | 70s, mild year-round |
| Insurance Exposure | Often highest — FAIR Plan common in Cambria's wooded areas and on bluffs | Varies by parcel and hazard zone | Varies by parcel — in-town lots often lower, rural and foothill parcels higher |
| Exterior Maintenance | High — salt air on paint, hardware, and roofing | Moderate | Moderate |
| Hospital Access | Morro Bay is a short drive to San Luis Obispo; Cambria is roughly 30 miles or more from the nearest hospital | Sierra Vista Regional Medical Center, French Hospital Medical Center, and specialty care | Arroyo Grande Community Hospital in the South County |
| Walkability | Varies — harbor and village cores walkable, outskirts not | Strongest in the county — downtown San Luis Obispo | Arroyo Grande Village walkable; Nipomo largely car-dependent |
| Best For | Buyers prioritizing view and accepting higher carrying costs | Buyers prioritizing services and walkability | Buyers prioritizing climate balance and value |
The row that surprises buyers most is insurance exposure. It’s the one line where the premium coastal address can quietly reverse the math on an otherwise stronger property.
None of that means don’t buy the view. It means buy it knowingly — as a lifestyle choice you’re making with clear eyes, not on the assumption that the coastal premium always pays off. We run the full cost picture with our clients, not just the purchase price, so the decision is grounded in data rather than a first impression.
- Does this location still work in ten years?
Two things belong on the table before you fall in love with a property.
The first is hospital access. San Luis Obispo has Sierra Vista Regional Medical Center, French Hospital Medical Center, and access to specialty care, and the South County has Arroyo Grande Community Hospital. Cambria, which is genuinely peaceful, sits roughly 30 miles or more from the nearest hospital. That doesn’t disqualify it — it’s a fact worth knowing while you still have options. Ask yourself: if my health situation changes five or ten years from now, does this location still work?
The second is the shape of an ordinary week. I’ve worked with buyers who bought a beautiful, quiet property for the view in an area with almost no walkability, and more than a few called me within two years ready to sell. What holds up over time is having a reason to leave the house — walking to coffee, a wine bar you can reach on a Tuesday, a farmers market where you run into people you know.
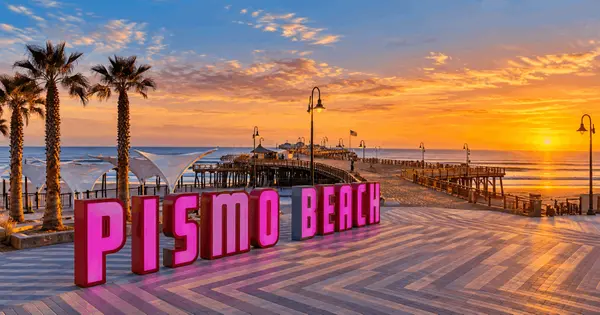
Downtown San Luis Obispo is the most walkable hub in the county, and its Thursday night farmers market draws thousands of people to five blocks every week. Arroyo Grande Village has a swinging footbridge and a Saturday market in the village itself. Pismo Beach and Shell Beach carry a classic beach town feel — more resort than deep roots, but still walkable. Morro Bay is laid back and built around the harbor, with its own market twice a week.
Many of the buyers we work with are also rethinking what a home should do for them. Single-level homes, condos, and townhomes with minimal yard and low exterior maintenance — lock-and-leave living you can close the door on and travel for three months — are drawing buyers who once would have chosen size and land.
So ask yourself: on a random Wednesday, what does my day look like? If the honest answer involves a lot of driving and a lot of quiet, that’s information worth having now.
Frequently Asked Questions
Is San Luis Obispo County a good place to relocate to?
For most relocating buyers, yes — but the fit depends on pace, not scenery. San Luis Obispo County moves at a slower, small-town rhythm and sits roughly three and a half to four hours from both Los Angeles and San Francisco. Buyers coming from a major metro who want constant culture and plans on demand sometimes find the adjustment isolating before it feels peaceful. The ones who thrive here wanted the slower life, not a better view of the one they already had.
How much does California FAIR Plan insurance cost in San Luis Obispo County?
It varies widely by property, brush score, and insured value. In Cambria, where 344 homes carried FAIR Plan policies as of May 2026, the average premium was projected to rise from about $3,122 to roughly $3,999 a year after the 29.1% average FAIR Plan rate increase that took effect October 15, 2026. High-wildfire-risk properties can see more than the average. Confirm your specific number with a licensed insurance agent before you write an offer.
Does Proposition 19 help if I’m moving within California?
It may, depending on your circumstances. Proposition 19 can allow you to transfer your existing property tax base-year value to a replacement home rather than resetting to the purchase price, which can materially change annual carrying cost on a home above $1 million. Eligibility rules, timing windows, and value adjustments all apply. Confirm your situation with your CPA or the San Luis Obispo County Assessor before you build it into your budget.
Is it better to buy coastal or inland in San Luis Obispo County?
Once you factor in insurability, exterior maintenance from salt air, and long-term resale, a well-positioned inland property in San Luis Obispo or Edna Valley can be the stronger financial decision. Coastal remains the right choice for buyers who want the view and have modeled the carrying costs honestly. The mistake is assuming the coastal premium recovers itself automatically at resale.
What should I confirm before writing an offer on the Central Coast?
Confirm the Cal Fire hazard zone status and insurance cost, review the Transfer Disclosure Statement and all hazard disclosures during your contingency period, and build a full carrying cost model that includes property taxes, HOA dues, documentary transfer tax, and exterior maintenance. Also confirm your distance to hospital care and what your ordinary week looks like from that address.
Getting the Move Right
Know the trade you’re making before you make it. Know your microclimate and your insurance picture before you fall for a view, know the full cost picture rather than the purchase price, and know how you’ll spend an ordinary Wednesday ten years from now.
Those four answers are the difference between a move that holds and a move that unwinds — and they’re exactly what we work through with relocating buyers before we ever start touring properties.
Considering a move to San Luis Obispo County? Explore our free Central Coast Relocation Guide: raymondteamre.com/the-central-coast-relocation-guide
Ready to talk through your situation? Schedule a meeting with the Raymond Team — call us at 805-201-6341, or book a Zoom at book.raymondteamre.com.
About Ruby Raymond
Ruby Raymond is an SRES and Certified Probate & Trust Real Estate Specialist serving San Luis Obispo County, with a wealth of experience in lifestyle relocations. She helps clients navigate major transitions with clarity and confidence, ensuring each move aligns with their next chapter. With a background in probate and trust sales, she brings precision and care to complex transactions, working closely with attorneys, CPAs, and trustees when needed — so you can move forward with confidence at every stage